Market Insights
Market Information Friday 16 October 2026
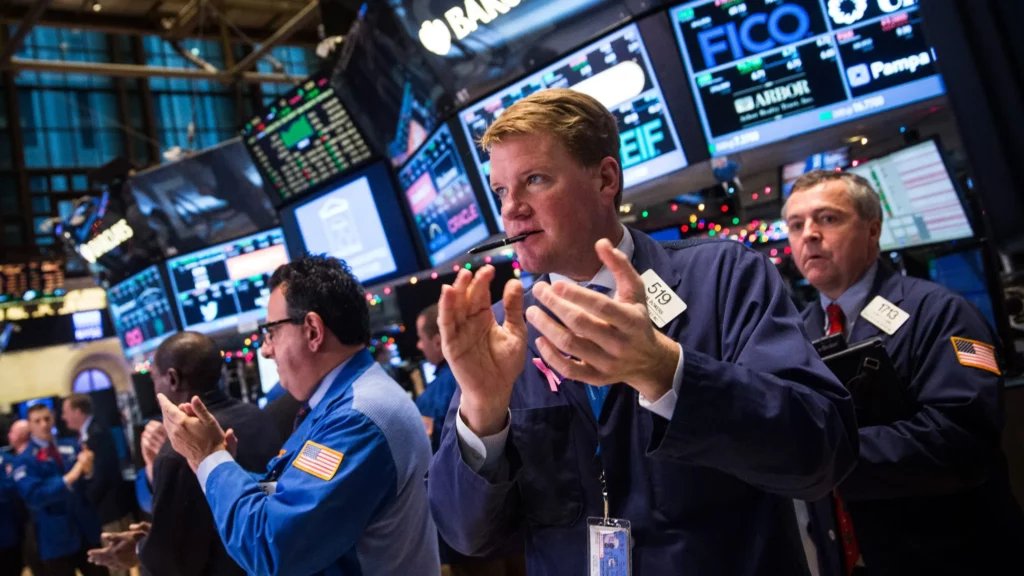
US equities recovered from early losses on Thursday as investors shifted away from rate-sensitive technology stocks towards more defensive sectors, with the S&P 500 closing 0.33% higher and the Dow gaining 1.08%. Semiconductor stocks declined for a seventh consecutive session, while persistent inflation and elevated borrowing costs continued to raise concerns about highly capital-intensive technology investment.
US producer prices rose sharply in September as record-high diesel costs spread through freight, agriculture and manufacturing, increasing the risk of further consumer price pressures. Freight transport costs climbed 19% year-on-year, while early-stage food input costs rose 15.6%, suggesting elevated energy prices could increasingly feed into food and goods inflation. Persistent cost pressures may reinforce expectations that US interest rates will remain higher for longer.
The US is expanding strategic reserves of critical minerals as tight global copper supply and trade uncertainty raise concerns about access to materials essential for power infrastructure, data centres and manufacturing. Copper prices have approached $15,000 per tonne, while approximately $7 billion of copper has flowed into the US since late June amid expectations of potential tariffs. The development reflects the growing economic importance of securing critical mineral supply chains as structural copper shortages emerge.
The 6M Euribor increased with 1 basis point to 2.92% compared to previous business day. The 10Y Swap decreased with 5 basis points to 3.50% compared to previous business day.
In the attachment, today’s market data on money and capital market rates as well as other rates are presented.